Italian Sea Group Reports €292.3m Overdue Liabilities at September End
By Stephen Yardley · Edited by Stephen Yardley
The Italian Sea Group's 30 October 2026 regulatory disclosure sets out €292.3 million in overdue consolidated liabilities at 30 September, €184.2 million in net financial indebtedness and outstanding creditor proceedings as its restructuring continues.
The Italian Sea Group has published a detailed update on its financial position as at 30 September 2026, placing consolidated overdue liabilities at €292.303 million. The disclosure, issued on 30 October in response to a request from the Italian securities regulator Consob, also records net financial indebtedness of €184.211 million and cash of €1.926 million at group level. These are different accounting measures and must not be added together to suggest a larger single debt figure. The company describes the financial-position information as unaudited, an important qualification for anyone using the figures to assess its restructuring.
The report concerns the business behind the Admiral, Tecnomar, Perini Navi and Picchiotti yacht brands, as well as NCA Refit. It follows months of negotiations with creditors and a court-supervised process in Florence. These developments matter to owners and suppliers because a large custom yacht depends on staged payments, specialist contractors and a long chain of commitments. However, the disclosed numbers do not by themselves establish the status of any individual build, the treatment of a particular supplier contract or the outcome of the restructuring. Those matters require project-specific confirmation.
According to the official filing, consolidated financial indebtedness net of liquidity stood at €184.211 million on 30 September. The group reported €150.365 million in bank borrowing, with those loans classified as current following non-payment of instalments, including instalments on facilities originally arranged for longer terms. It also listed a €25 million shareholder loan from GC Holding and €9.239 million of non-current lease liabilities. Total cash and cash equivalents stood at €1.926 million. The parent company's corresponding net financial indebtedness was €184.386 million, with €1.751 million of cash.
It would be misleading to compare the cash figure solely with a bank instalment and assume an immediate liquidation outcome. A restructuring process involves negotiations, timing of receipts, asset transactions and the treatment of existing obligations. Equally, the classification of borrowing as current is a serious disclosure because payment defaults can change the rights available to lenders. The company states that its figures follow the relevant European net-financial-position reporting framework where applicable. They give a more structured picture than an unsupported assertion that the shipyard is simply either operating normally or no longer viable.
The group's overdue liabilities total breaks down into €54.721 million of financial liabilities, €95.162 million of accounts payable, €100.157 million due to factoring companies, €20.661 million of tax liabilities and €21.602 million of social-security liabilities. The disclosure reports no overdue amounts due directly to employees in that table. These categories sum to €292.303 million. The report defines overdue liabilities as obligations whose payment date has passed without settlement, rescheduling or other discharge, and distinguishes that total from net financial indebtedness under the separate reporting methodology.
That distinction is especially relevant for the yacht-building supply chain. Some reverse-factoring and confirming balances associated with suppliers are classified as trade payables and excluded from the company's calculation of net financial indebtedness. Counting them again as extra bank debt would confuse two presentations of obligations. The report also explains that certain earlier supplier settlement arrangements, which included partial write-offs and rescheduled balances, were reinstated in the accounts after the move into the Article 44 pre-filing proceedings. A reader should therefore examine the nature of each figure before making comparisons with an earlier monthly report.
Of the €150.365 million of bank borrowing, the group states that €54.721 million was overdue and €95.644 million had not yet fallen due. It says missed principal payments and covenant breaches could entitle banks to demand immediate repayment of remaining amounts, but that lenders had not exercised this right as at the report, in the context of restructuring discussions. This is a crucial limit on the interpretation of the filing: the existence of a potential contractual remedy is not the same as a statement that all lenders have already called their loans.
The document also records 46 payment orders served on the parent company since 16 March, representing claims of €2.416 million; 23 had been settled for a final agreed total of €414,000. Other orders were being challenged, negotiated or addressed through restructuring discussions. Separately, two suppliers had filed petitions seeking the commencement of judicial liquidation proceedings, with claims totalling €575,000. The company says the relevant hearing was adjourned to 11 November 2026. These are reported proceedings and applications, not proof that the court has ordered liquidation.
The September update gives specific information on TISG Turkey. It says a supplier called on a €260,000 bank guarantee in connection with an approximately €400,000 outstanding debt and that the guarantee was honoured in September. Six further precautionary enforcement actions by other suppliers sought recovery of a combined €4.25 million; according to the company, those proceedings were stayed after formal objections. Two suppliers also sought precautionary attachment measures concerning yacht number 613, machinery or other tangible assets, with one described claim of €1.599 million and another of approximately €300,000.
These are legally sensitive matters and the company's account should be read with care. A precautionary application is not the same as a final finding on the merits of a supplier claim, and a stayed proceeding has not necessarily been resolved permanently. The official update also refers to protective measures affecting the Italian company and Celi, with different dates and legal frameworks applying. The practical significance for project participants will depend on contractual arrangements, local proceedings and subsequent orders. No conclusion about ownership or delivery of a particular yacht can responsibly be drawn from the headline figures alone.
The financial disclosure follows a separate company announcement on 19 October confirming five binding offers in its search for investors. The Italian Sea Group said all five were structured as asset deals and that two concerned the acquisition of the entire business. It named Meti Corporate Finance and KPMG Advisory as advisers to the board's evaluation process. The bidders' identities and transaction terms were not disclosed in that announcement, and the company had not thereby announced a completed sale. The status of the offers should be checked against subsequent regulated notices rather than inferred from market speculation.
The Florence court granted an additional 60-day extension in September for preparation of the company's restructuring material and scheduled a hearing on 11 November to consider the plan and associated business plan. The outcome remains subject to the formal process and any further company disclosures. For owners, crew and contractors, the sensible questions concern confirmed project schedules, payment arrangements and operational continuity, not speculation about which brand might change hands. The 30 October figures sharpen the financial picture but do not settle the restructuring. Further official filings and court developments will be more informative than any prediction of a buyer or result.
Primary disclosure: The Italian Sea Group, 30 October regulated financial update. Related 19 October binding-offers announcement.
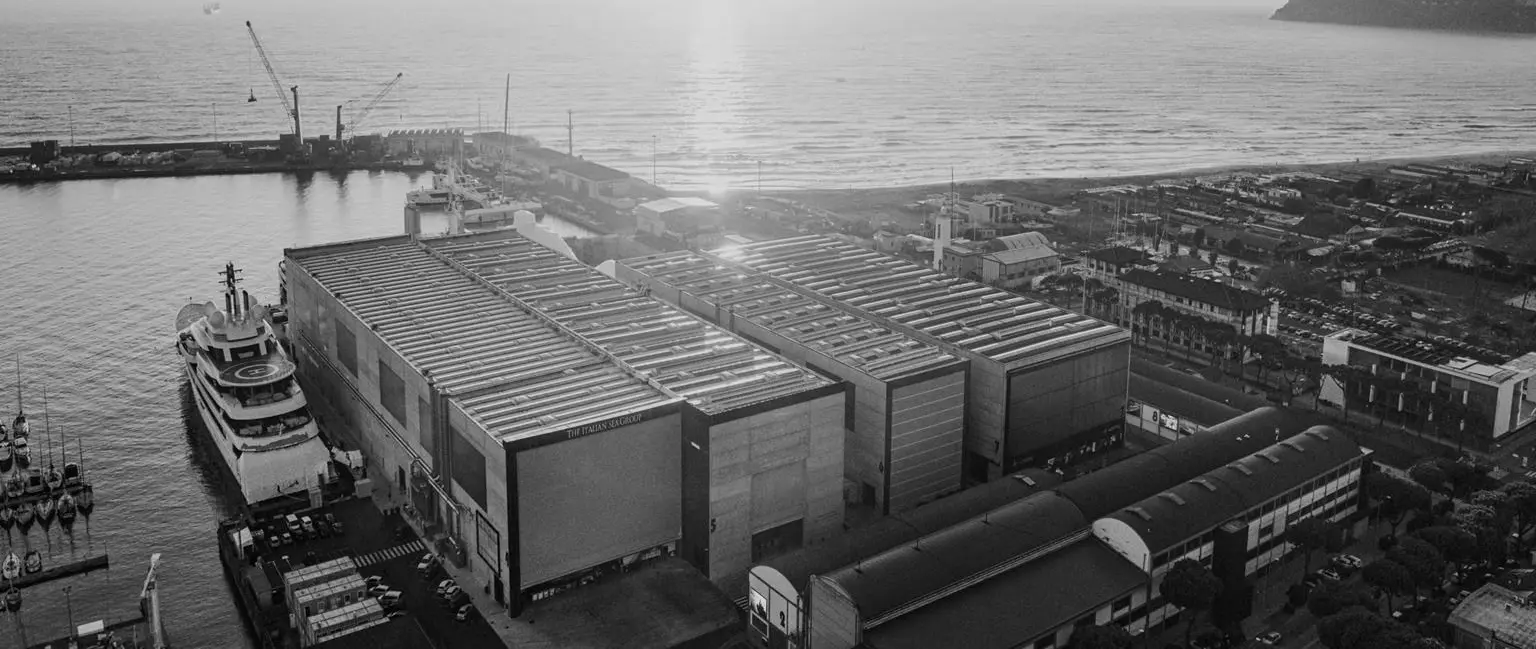
Archive picture source: The Italian Sea Group official 2024 annual financial report; the image is illustrative and is not a photograph of September 2026 events.
Explore
Go deeper into the yachts, companies, events and destinations directly connected to this article.
Continue reading
The Italian Sea Group reappoints founder Giovanni Costantino as CEO, creates new board committees and moves half-year reporting to 3 November.
The Italian Sea Group has reported a €170.9 million consolidated net loss for 2025, with revenue down 27% to €295.1 million.
The Italian Sea Group has received 11 non-binding offers in its investor process. Selected bidders will proceed to due diligence ahead of a 15 …
The Court of Florence has granted The Italian Sea Group another 60 days to file its definitive restructuring plan and proposal under Article 44 …
Superyacht Guide
Continue into the wider Superyacht Guide.
Business opportunities · Superyacht Guide
Companies serving the superyacht market can discuss clearly identified advertising, sponsorship and business-profile opportunities. Commercial activity remains separate from independent editorial coverage.