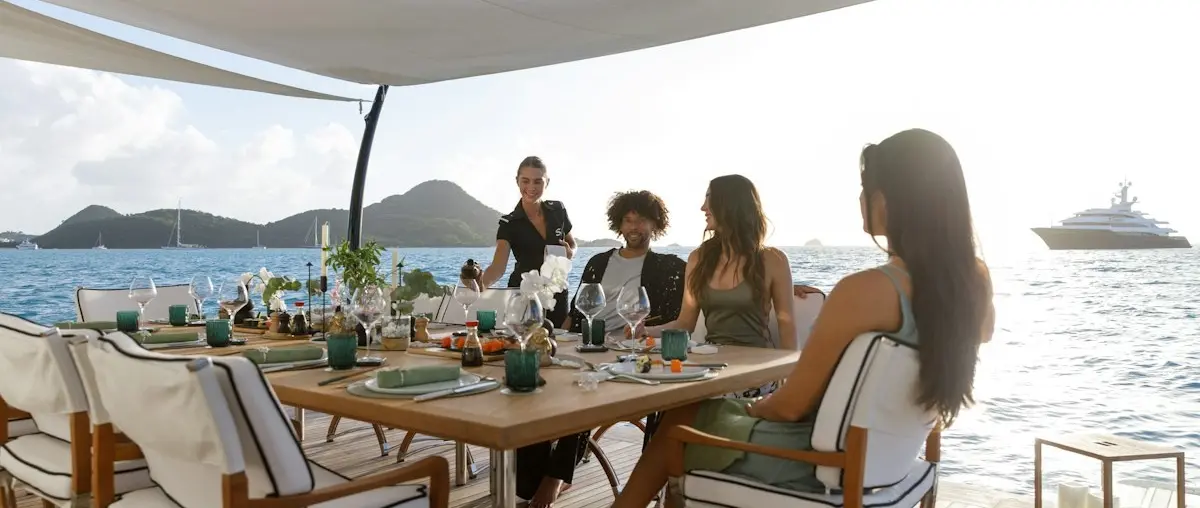
Charter Demand Rises as the Existing Superyacht Fleet Carries More Booked Days
By Superyacht Guide Newsroom · Edited by Superyacht Guide Newsroom
Northrop & Johnson November 2026 charter market report official editorial photograph
Northrop & Johnson's October market update finds charter activity rising much faster than participating fleet size, while early 2027 reservations are fewer but longer.
Northrop & Johnson's 16 November report identifies a striking divergence between the growth of charter bookings and the increase in the number of participating yachts during the first ten months of 2026. In the brokerage's recorded market, reservation volume grew by roughly 27 percent, while the number of individual participating vessels rose by approximately three percent. The difference merits particular attention from yacht managers and owners because expanding demand does not necessarily translate into a proportionately larger charter fleet. Instead, a substantial part of the additional business appears to have been accommodated by yachts already operating in the market. The interpretation is important when considering management priorities for the forthcoming season. An increase in charter activity can be desirable commercially, but the capacity to accommodate a greater number of guests depends on the operational readiness of each vessel and the availability of personnel and supporting infrastructure.
The brokerage records 8,247 reservations and 74,242 booked days across 1,635 distinct yachts during January through October. These measures describe different aspects of commercial activity. A booked day is a unit of reservation duration, rather than an independently confirmed day during which the vessel was physically occupied. The number of reservations does not establish the number of individual clients, because some clients can make more than one booking. Similarly, a participating yacht is not necessarily available for commercial operation throughout the entire reporting period. The data can therefore support an analysis of the relationship between recorded reservations and participating vessels without establishing fleet-wide occupancy as a proportion of every day theoretically available. The report does not quantify unrecorded transactions or publish a complete methodology for reconciling cancellations. Its totals should consequently be attributed to Northrop & Johnson rather than treated as independently audited figures for every commercial yacht worldwide.
Dividing the reported booked days by the number of participating yachts yields approximately 45 booked days per vessel on average. This figure is useful as an aggregate indicator, but it does not describe the booking calendar of a typical individual yacht. A vessel newly introduced to charter late in the period would have a different number of available days from one operating continuously since January. Others might leave the market for technical work or because their owners reserve substantial portions of the season for private use. A small group of intensively utilised yachts could also contribute disproportionately to the arithmetic average. An analyst examining the commercial performance of an individual vessel should therefore compare recorded charter days with that vessel's actual availability, rather than use the aggregate number as a universal target. The difference between market growth and growth in fleet participation is nonetheless significant: it suggests that the operational performance of existing yachts deserves at least as much attention as the introduction of additional supply.
A busier charter calendar has practical consequences for the management of assets. Repeated periods of guest occupancy can reduce the opportunities available for nonessential technical work and the renewal of decorative finishes. The interval between successive charters may be short, especially in a season characterised by concentrated demand. An engineering team must therefore plan servicing around both the vessel's operational requirements and the commitments accepted by its commercial representatives. Certain routine inspections can be conducted while the vessel is available to guests, whereas others require systems to be taken out of service. The physical movement of tenders, cleaning equipment and contractors can also conflict with the use of guest-facing spaces. Owners should consider these operational constraints when evaluating the benefit of additional charter revenue. A successful commercial programme depends on the reliability of the accommodation and machinery over the season rather than solely on the number of reservations entered in the calendar.
For winter 2026/27 the report records 812 reservations, of which 547 are associated with the Caribbean and The Bahamas. This geographical concentration has implications for the deployment of yachts and delivery of the services on which their operation depends. A yacht positioned on the opposite side of the Atlantic must allow for mobilisation, ocean passage, preparation and the rest requirements of its crew. A promising reservation cannot automatically be considered profitable without assessing the cost of making the vessel available in the destination. For vessels already based in the region, the concentration of charter activity may increase demand for local berths, provisioning and technical support. Operators should establish those arrangements in advance, particularly where a sequence of bookings involves changes of embarkation location. The reported reservation figures do not establish actual availability of berths or support services in particular destinations. Those details must be confirmed through the vessel's local contacts rather than inferred from the broader trend.
Northrop & Johnson's early figures for 2027 indicate fewer reservations than were recorded for 2026 at the equivalent point in the previous year. However, their combined duration is much closer to the comparative total. The advance market is therefore showing a difference in the composition of demand rather than an equivalent decline across every measure. A longer reservation can have operational advantages, such as reducing the number of handover periods, but that does not guarantee that the booked time will produce a higher financial return. The particular rate, applicable expenses and commercial terms remain important. The brokerage data also indicates substantial advance interest in the eastern Mediterranean and Adriatic. Yacht managers considering deployment in these areas should examine the practical requirements of their itineraries, including the possibility of consecutive bookings in different jurisdictions. Advance market data is a provisional snapshot and cannot establish the eventual geographical distribution of the completed 2027 season.
The report indicates that vessels of 40 metres and above account for approximately 57 percent of the reservations already recorded for 2027. This is relevant to the management of larger yachts, for which a booking can involve particularly extensive logistics. Transfers of guest luggage, shore arrangements, specialist provisions and the movement of tenders may require considerable coordination. An extensive itinerary can also create a need for multiple confirmations of destination permissions, access and support. Larger yachts may have limited berth choices in some cruising areas, making decisions about anchoring and transfer arrangements particularly important. A high proportion of advance reservations in larger length categories should not be interpreted as a universal increase in demand for every yacht of that length. Design, reputation, actual availability, operating costs and the individual terms of the charter may all affect the commercial appeal of a vessel. The reported distribution is best understood as a measure of bookings within the brokerage's dataset.
Charter managers can use the market report to reconsider the relationship between the timing of marketing activity and the timing of technical and crew commitments. It may be appropriate to specify maintenance periods before accepting additional reservations, rather than attempt to fit all technical work into residual gaps. Owners should make clear which dates are genuinely available for commercial use and which may be required for their own travel. Otherwise, a busy market can create tension between the desire to secure bookings and the need to preserve flexibility. The charter representative, captain and yacht manager each possess different information relevant to these decisions. Their assessments should be reconciled before commitments are made, particularly when repositioning or substantial preparation will be required. A longer booking may simplify some aspects of scheduling yet introduce demanding requirements for provisions, fuel, maintenance or crew rotation depending on the intended itinerary.
The published figures describe a market that has recorded significantly more charter activity over the first ten months of 2026 despite a relatively modest rise in participating fleet size. The advance calendar for the following year is not yet sufficient to establish whether the growth will be sustained. Further bookings, cancellations and changes to the supply of commercially available yachts can alter the picture before the next season begins. Operators should track both booked days and vessel availability, alongside the expenses and operating conditions associated with those commitments. The data is most useful when treated as a starting point for informed planning rather than a prediction of the financial performance of an individual yacht. The November report reinforces a distinction that is sometimes obscured by discussion of the size of the charter fleet: the commercial opportunity presented by each vessel depends in part on how successfully its available time can be managed and delivered.
Primary source: Northrop & Johnson official charter-market analysis, 16 November 2026.
Photography: Jeff Brown, courtesy of Northrop & Johnson; illustrative image supplied with the charter report. Official source.
Explore
Go deeper into the yachts, companies, events and destinations directly connected to this article.
Continue reading
Northrop & Johnson data shows global yacht charter starts up 20.8% through August 2026, while the market splits between late bookers and early 2027 …
Northrop & Johnson reports 6,036 worldwide charter starts in January–July 2026, up 30.5%, with more guests booking closer to departure.
The 32m Monte Carlo Yachts motor yacht CIELO NERO joins Northrop & Johnson's Bahamas charter fleet from $90,000 per week after a 2024 refit.
Burgess says charter days booked increased 35% in 2025, with demand also rising in the 40–60m sectors and winter 2026/27 bookings well ahead of …
Superyacht Guide
Continue into the wider Superyacht Guide.
Business opportunities · Superyacht Guide
Companies serving the superyacht market can discuss clearly identified advertising, sponsorship and business-profile opportunities. Commercial activity remains separate from independent editorial coverage.
