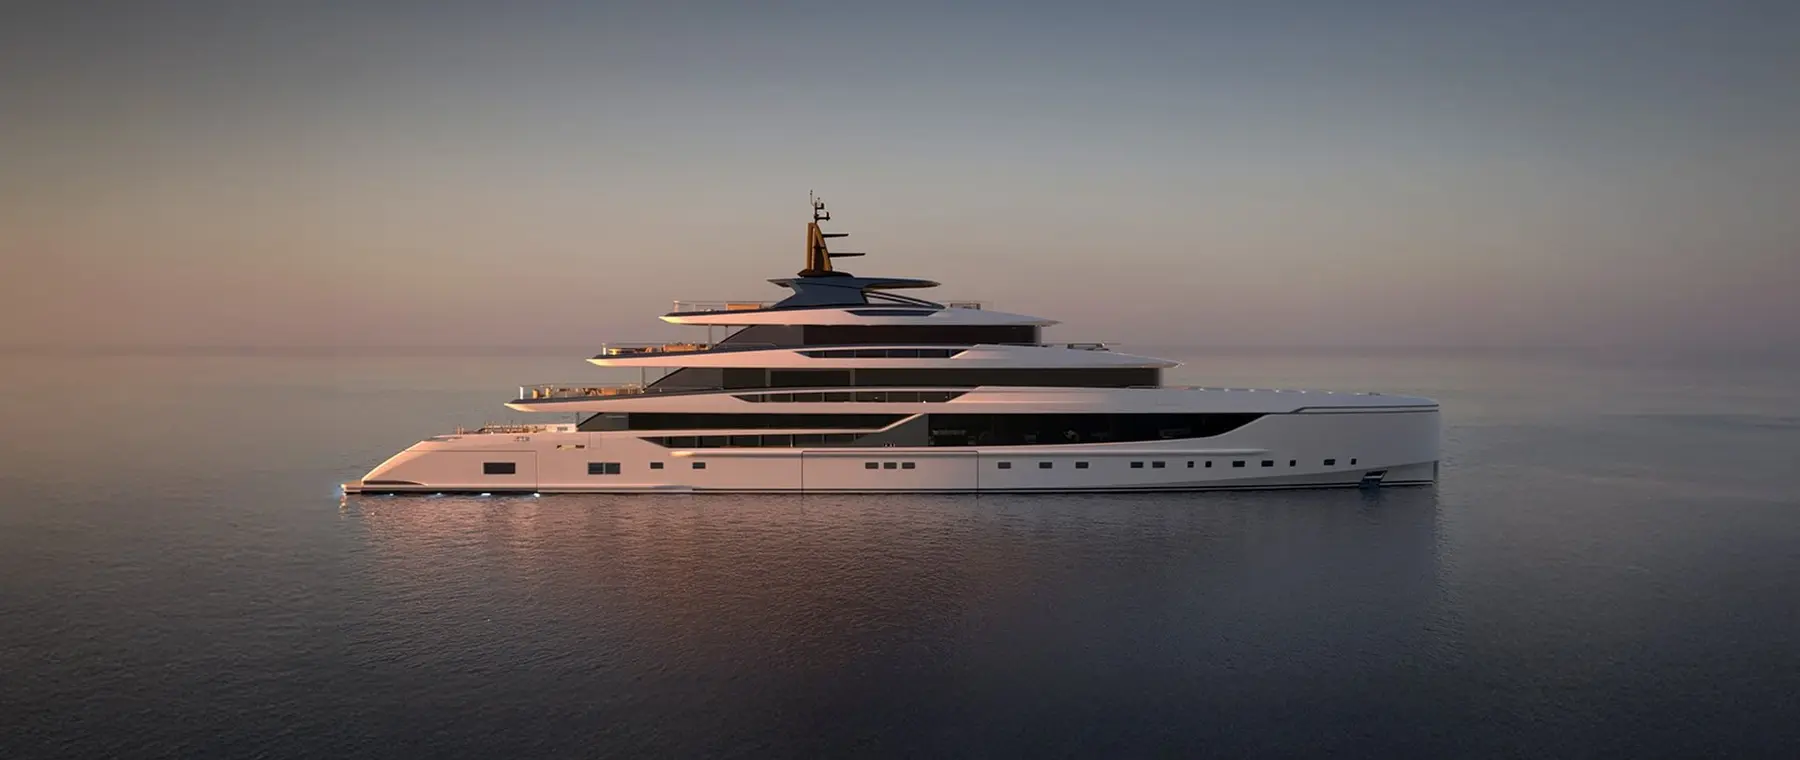
Sanlorenzo 74Steel superyacht, illustrative official company fleet photograph

News

Sanlorenzo Reports €803.1m Order Intake as Superyacht Division Grows 8.9% in Nine Months

Nov. 13, 2026 Business

Sanlorenzo 74Steel superyacht, illustrative official company fleet photograph

Sanlorenzo's nine-month results show €803.1m of orders, an €1.81bn backlog and 8.9% growth in its Superyacht Division, as cash generation improves.

A stronger order book than headline revenue growth suggests Sanlorenzo reported €803.1 million of order intake for the first nine months of 2026, a rise of 16.4% from €689.7 million during the same period a year earlier. The company released its figures on 12 November after approval by its board, chaired by Massimo Perotti. The result is particularly significant because new orders grew faster than the revenue recognised from yachts during the period. The company's net revenues from new yachts increased 3.1% to €711.3 million. Those measures describe different things: order intake indicates signed commercial activity, while revenue reflects accounting recognition as construction progresses. Neither figure is a count of completed or delivered superyachts.

Superyachts provide the clearest divisional growth The group's Superyacht Division generated €226.0 million of net revenue in the first nine months, up 8.9% year on year from approximately €207.6 million. Its share of group net revenues from new yachts increased to 31.8% from 30.1%. This makes the larger-vessel operation an important driver of growth, even though the wider Yacht Division remains bigger in absolute revenue. Sanlorenzo attributes its performance partly to demand for larger yachts and to work already contracted over extended delivery periods. It would be incorrect to interpret the 8.9% rate as growth in the entire global superyacht market. It is a result for this one publicly listed builder, operating with its own product mix, order book and accounting approach.

What the €1.8bn backlog actually represents Sanlorenzo disclosed an order backlog of €1,805.6 million at 30 September, 5.6% higher than the prior-year figure of €1,709.4 million. Management said that approximately 89% of the backlog related to contracts already sold to final clients. Net backlog, defined as contracted revenue yet to be recognised, stood at €1,094.3 million, up 7.4% year on year. The distinction between gross and net backlog is central to understanding the release. Gross backlog is not the same as unpaid profit or free cash. A backlog carries production obligations and may be influenced by scheduling, costs, contractual terms and the timing of completed work.

Visibility into the 2027 construction programme The company reported that €924.5 million of backlog related to 2026 and €881.2 million to later years. It said the current-year backlog represented around 92% of the midpoint of its guidance for 2026 net revenues from new yachts. In practical terms this gives management visibility over factory scheduling and future workload, though it is not a guarantee that every contract will progress exactly on time. Large custom yachts involve design, class, supply chain, owner decisions and sometimes significant changes during production. Owners considering a newbuild should distinguish between an established delivery slot and the date a fully completed yacht will be accepted after testing and handover. The order book offers context, not an individual contract warranty.

Revenue is rising, but margins deserve attention Group EBITDA reached €131.2 million, up 2.5% from €128.0 million a year earlier. The EBITDA margin was 18.4% of net revenues from new yachts, compared with 18.5% in the previous nine-month period. Operating profit rose 1.8% to €99.4 million, with an EBIT margin around 14.0%. Group net profit increased 4.1% to €79.1 million. These are respectable figures, but the slightly lower percentage margins are a useful reminder that rising sales do not automatically translate into proportionate profit expansion. Production complexity, pricing, financing and the exact mix of vessels in build can influence returns. A serious assessment therefore considers all four measures rather than treating the order-intake increase as a complete financial verdict.

Cash generation improves markedly Perhaps the release's clearest balance-sheet improvement is free cash flow, reported at €77.2 million versus an outflow of €12.6 million in the comparable 2025 period. Operating cash flow was €102.5 million, compared with €16.2 million a year earlier. Sanlorenzo attributed the improvement to operating profitability, reduced absorption of working capital and stronger order intake. At 30 September it reported a net cash position of €56.0 million after €37.1 million of dividends during the first nine months. Financial flexibility matters to owners because yacht construction requires suppliers, skilled labour and long lead-time equipment before projects generate their final cash receipts. Nevertheless, the listed company's balance sheet is not a substitute for contractual protections in any particular newbuild agreement.

The Americas and Asia-Pacific change the geographic mix The geographic breakdown shows how Sanlorenzo's customer-facing business is evolving. Revenue attributed to the Americas reached €188.7 million, up 34.5%; Asia-Pacific reached €108.9 million, up 57.5%; and the Middle East and Africa reached €47.6 million, up 12.9%. Europe, although still the largest region at €366.1 million, declined 16.5% against a stronger comparison period. Outside Europe, the group generated 48.5% of net revenues from new yachts compared with 36.5% a year earlier. These numbers show the revenue distribution reported by Sanlorenzo, not necessarily where yachts cruise or where their owners reside throughout the year. For the service industry, the geographic shift raises questions about distribution, after-sales support and technical coverage across distant operating areas.

What this means for owners and brokers A stronger non-European mix can require additional regional capacity for commissioning, warranty work, survey support and servicing. Owners purchasing a yacht from an international brand may expect after-sales responsiveness wherever they keep the vessel, but actual arrangements differ between countries and models. Sanlorenzo's reported network, including the Simpson Marine distribution platform in Asia-Pacific, helps explain its strategy of managing closer contact with clients. For brokers, headline sales figures may indicate brand momentum, but they cannot establish a price trend for used yachts without transaction-level comparisons. A healthy builder order book and a strong resale market are related only indirectly, with different supply, demand, age and condition factors.

Sanlorenzo's 74Steel and larger-yacht strategy The operational section of the release highlights the 74Steel flagship and its two very different owner-oriented expressions, SILVER FOX and VIRTUOSITY. It also refers to a broader emphasis on larger yachts, engineering flexibility and highly personalised onboard environments. The 74Steel references are relevant because the company is explicitly linking financial growth with its superyacht capabilities. An accompanying fleet photograph should be identified as an illustrative Sanlorenzo press image rather than a picture taken at the results briefing. The market significance of a flagship extends beyond its gross tonnage. It shows what a builder can coordinate in architecture, structure, systems and owner-specific interior programmes, all of which affect project complexity and production resources.

The business extends beyond motor superyachts The report also covers the Yacht Division, Bluegame and Nautor Swan. The Yacht Division recorded €359.5 million of revenue, up 4.2%; Bluegame recorded €66.4 million, up 1.5%; and Nautor Swan contributed €59.4 million, down 17.6%. The softer Swan figure was reported during a continuing integration and product-development period, with management pointing to more recent Q4 activity. The group also said nine examples of the Sanlorenzo SHE heritage yacht had been sold by the release date. These programmes operate across different boat sizes and markets. Superyacht Guide should not assume that every product below 24 metres belongs in its superyacht coverage simply because the parent group reports consolidated numbers; here the group data provides essential corporate context.

Guidance remains unchanged Sanlorenzo reaffirmed its full-year 2026 outlook, setting net revenues from new yachts at €980 million to €1.02 billion, EBITDA at €180 million to €192 million, and group net profit at €108 million to €114 million. The company also reiterated longer-term targets from its 2026–2028 business plan. Guidance represents management's expectations on the information available at the time, not achieved results or a guarantee. Investors and suppliers will watch for subsequent changes in order intake, production schedules and cash generation. For clients commissioning sophisticated yachts, the more immediate issue remains whether their builder can deliver a technically sound and well-supported vessel in accordance with the agreed scope and schedule.

A disciplined reading of the nine-month report The central news is that Sanlorenzo's order activity outpaced the revenue growth visible in its nine-month accounts while the Superyacht Division provided an important portion of expansion. Its backlog, profitability and improved cash generation together offer a more rounded picture than the order total alone. There is also a geographical story, with faster reported growth in the Americas and Asia-Pacific offsetting a European decline. None of these figures means the wider yacht industry is universally booming, and none permits an estimate of individual owner demand without further evidence. What can be said is that this builder entered the final quarter with substantial contracted work and reaffirmed financial guidance.

Verification and editorial limits All financial figures refer to the nine months ended 30 September 2026 and are taken from Sanlorenzo's company-issued 12 November release. Sales and revenue are not interchangeable; estimates and guidance are not audited full-year outcomes. The source describes the 74Steel as an operating and product-development highlight, not a new launch occurring on the results date. An official 74Steel photo is therefore contextual and should be captioned accordingly. Owners, brokers and industry readers can use the results to understand the builder's direction, but should consult the complete company release for accounting definitions and investment decisions.

**Primary source:** Sanlorenzo S.p.A., 9M 2026 Financial Results, 12 November 2026. **Image:** Official Sanlorenzo 74Steel press photograph used illustratively for the group results; no image of the results presentation is claimed.

Primary source: Sanlorenzo S.p.A. 9M 2026 financial release.

Photo: Sanlorenzo official 74Steel press gallery; illustrative yacht photograph, not a 2026 financial briefing. Official press photograph.

Photo licence and source

Photo: Sanlorenzo official 74Steel press gallery; illustrative yacht photograph, not a 2026 financial briefing.

Continue reading

All news

Superyacht Guide

Explore the superyacht world

Continue into the wider Superyacht Guide.

Business opportunities · Superyacht Guide

Reach the superyacht industry audience

Companies serving the superyacht market can discuss clearly identified advertising, sponsorship and business-profile opportunities. Commercial activity remains separate from independent editorial coverage.