
Marine Results Gains Unrestricted RINA Approval for Superyacht Rigging Surveys
Marine Results International has become a RINA Approved Service Supplier for mast and rigging surveys with no restriction on yacht size or rig type, …
The Italian Sea Group's board has identified SRI Group Global Limited's €220 million proposal as the basis for its restructuring plan, while expressly reserving final buyer selection and court approval.
The Italian Sea Group, the Italian superyacht business associated with Admiral, Tecnomar, Perini Navi and Picchiotti, has selected an offer from SRI Group Global Limited as the reference bid for its restructuring plan. In a regulated announcement dated 2 November 2026, the listed company said the proposal covers the whole operating business and has an indicated consideration of €220 million. This is a consequential development after months of financial difficulty, but it does not mean SRI has bought the business. The company explicitly distinguishes its board's selection of a reference offer from legal acceptance, transfer and completion.
TISG is operating within proceedings before the Court of Florence under Italy's Crisis and Insolvency Code. The firm's 2 November release is the primary source for what has been decided and what remains conditional. A yacht owner with a project under construction should therefore not confuse the preferred proposal with a change in the company responsible for a vessel. Likewise, investors and suppliers cannot treat the headline price as money already received by the existing business. The next decisions depend on the court, negotiations with bidders and a further competitive phase.
The announcement follows the five binding offers disclosed on 19 October. TISG says its board compared those bids with assistance from advisers METI Corporate Finance and KPMG Advisory before choosing SRI's whole-business proposal as the foundation of its crisis-resolution plan. The release does not identify every bidder's terms or score one offer against another in public. Earlier industry commentary about possible contenders should not be elevated to a definitive list of accepted parties. The distinction between a bid and a successful acquisition is especially important in a court-supervised process involving working shipyards and contractual obligations.
The board has also resolved to reopen competitive bidding to seek improved terms for creditors and other stakeholders. If a stronger offer emerges, TISG says it intends to adjust the plan and proposal accordingly. Final selection of a purchaser is expressly reserved until that phase has finished and the company has assessed bidders' ability to meet their commitments. In practical terms, SRI has become the reference point against which alternatives can be examined, not an irrevocable winner. That makes the next formal disclosure more important than speculation about which other group might still participate.
Under the proposal described by TISG, the operating business would be sold to the purchaser currently provisionally identified as SRI for €220 million. A lease arrangement is envisaged for the period before a final sale, with the company expressing the view that a lease might be signed during the first week of December. Both steps remain prospective. A lease would allow a third party to run the business during the transition, whereas the eventual sale would transfer the relevant assets under the plan. The company has not announced that either stage is already effective.
The board characterises the chosen legal route as a composition with creditors involving indirect continuation of business activity. That means the industrial operation would continue under another operator rather than within the listed parent as before. The stated objectives include continuity of production and employment, subject to the applicable law and the final agreed structure. This is not evidence that every project delivery date or every supplier contract will remain unchanged. Owners and contractors should seek project-specific confirmation through the responsible commercial and legal channels instead of inferring their position from the public deal outline.
TISG's official release outlines how the proposed proceeds would be used under its planned creditor arrangement. Procedural expenses and other claims with priority would be covered in the stated manner, secured claims are proposed to be paid in full, and unsecured creditors would receive approximately ten percent. Subordinated creditors would receive no distribution under the current proposal. The company also proposes separating potential compensation and restitution claims into a trust, dedicated fund or other vehicle for creditors. Those terms are elements of a plan requiring scrutiny and authorisation, not completed payments.
Such categories matter in a yacht-building supply chain because a vessel is assembled through a network of specialist subcontractors, designers and equipment makers with potentially different contractual positions. The public release does not tell us which individual supplier falls into each class or whether particular project assets are covered by specific security rights. It would therefore be wrong to apply the advertised ten-percent figure automatically to every business that has dealt with TISG. Creditors need the actual plan, professional advice and their own documentation to establish how the proposed structure might affect them.
Another notable provision in the 2 November proposal is the absence of an allocation of value to shareholders. The company states that the listed parent would enter liquidation after the court confirms the composition and the plan is implemented, while the operating business passes to its purchaser. That would be a material corporate change even if the yacht-building brands, employees and facilities continue operating. However, it is still presented as an intended outcome of the restructuring, not as a liquidation already completed. Shares, assets and operating businesses are distinct legal interests in this process.
For readers following a public company, this is a reminder that continuity of a shipyard's productive activities does not necessarily preserve the existing shareholder structure. A buyer can acquire operating assets through a court-sanctioned arrangement without acquiring the parent company's shares. The information available here does not justify a prediction of future share prices, nor does it disclose the precise treatment of all existing contracts. The proper reporting focus is the structure, the conditional stages and the potential consequences for those with documented interests in the business.
TISG said the court filing was being made on 2 November, the end of a period granted under Article 44 of the crisis legislation. The company identified 11 November as the date scheduled for a hearing to review the proposed agreement. That hearing is a forthcoming procedural milestone, not an assurance that the transaction will be approved on that day. The formal authority to accept the selected offer also requires court permission under the legal framework cited in the release. Until the necessary authorisations have been obtained, the board's reference choice remains conditional.
The company has committed to informing the market of material developments through regulated disclosures. Owners, suppliers and employees should follow that sequence rather than assume that a news headline about a preferred bidder resolves the restructuring. It is conceivable that terms could change as bidding continues, but this article does not invent alternative prices or likely outcomes. The presently verifiable state is narrower: the proposal has a defined €220 million reference offer, a proposed creditor arrangement and a court timetable that governs what may happen next.
The same regulated announcement postpones the board meeting intended to approve the group's consolidated financial report for the six months to 30 June 2026. The meeting, previously scheduled for 3 November, has moved to 10 December. TISG says the delay will allow assessment of whether the business can prepare financial statements on a going-concern basis and how the restructuring affects its reporting. This does not provide a replacement set of audited financial results. It means that investors and commercial counterparties must distinguish the legal plan from financial disclosures still awaiting formal approval.
That reporting delay intersects with the company's separate preliminary September financial information, but the two documents answer different questions. A management filing prepared for the court addresses the company's position at a particular date, while a consolidated half-year report has its own accounting perimeter and review process. Combining figures from different scopes without explanation can produce misleading comparisons. A serious appraisal of the shipyard's finances will require the final published statements and any subsequent restructuring information, not an extrapolation from a single month's cumulative balances.
The Italian Sea Group's businesses operate in the construction and refit of large motor and sailing yachts. Active projects depend on experienced employees, equipment suppliers, design houses, classification and flag requirements, and customer funding agreements. The value of an uninterrupted industrial operation lies partly in maintaining those complicated relationships while a financial restructuring is examined. The current proposal is designed to preserve operations, but its public terms do not provide a yacht-by-yacht production schedule, a revised warranty arrangement or an assurance that no contracts will be affected. Each affected party needs direct communication supported by documents.
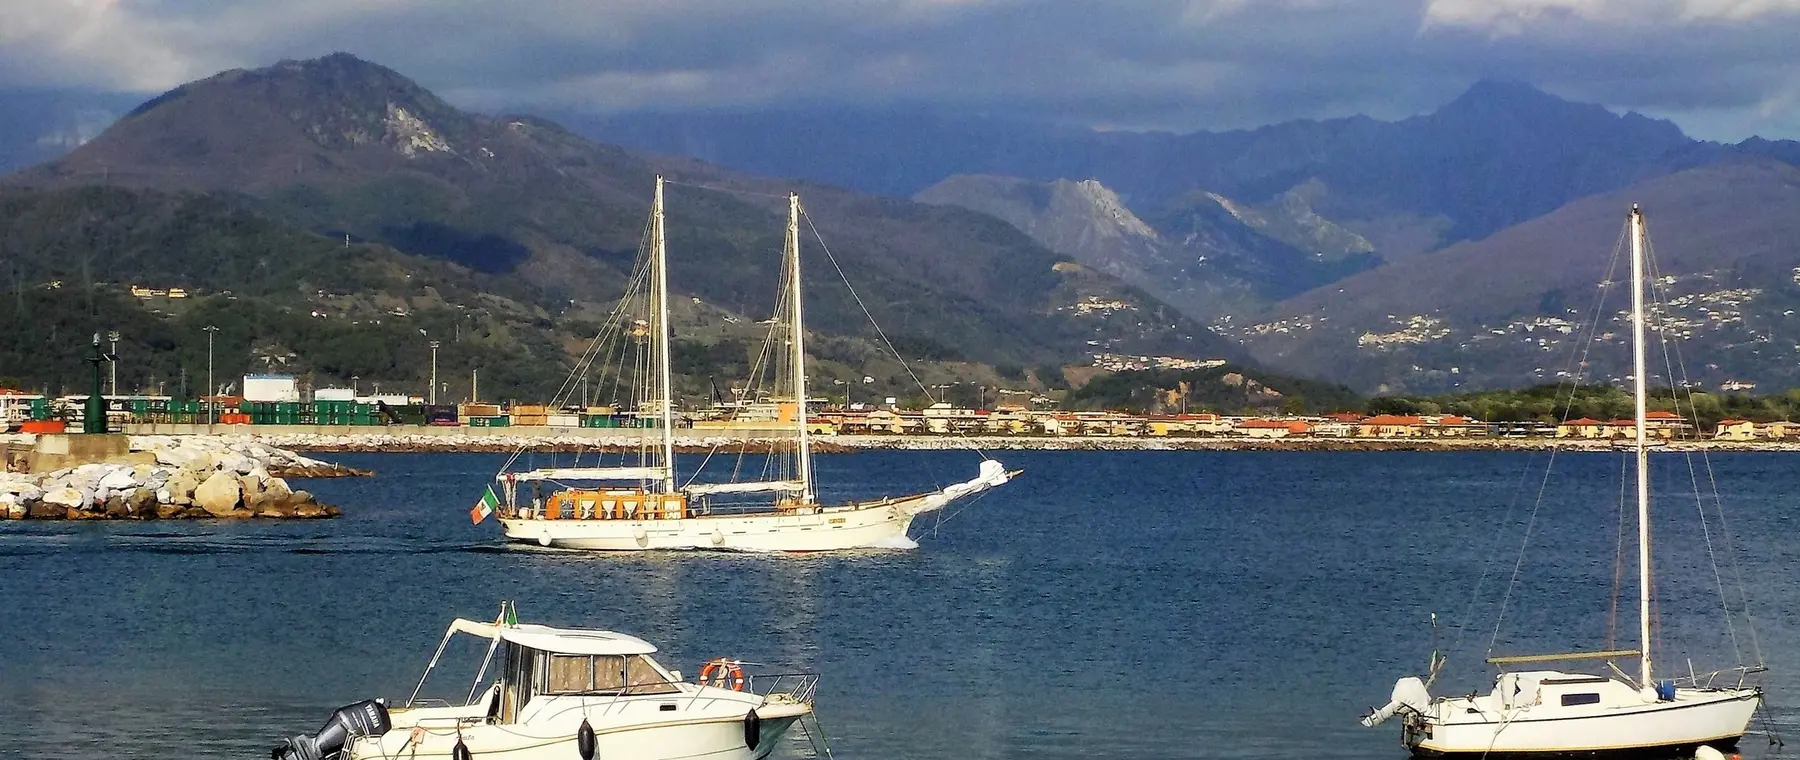
For the immediate news record, the decisive 2 November facts are clear: five binding offers were evaluated; SRI Group Global's whole-business €220 million bid has been designated as the plan's basis; the board favours indirect business continuity; additional bidding and court authorisations remain ahead; and 10 December is the revised reporting date. These facts are taken from the company's official regulated disclosure, also indexed by its investor-relations site. The accompanying archival image of Marina di Carrara is geographical context, not a photograph of an acquisition or the assets being transferred. Readers should expect further updates around the court process.
Primary source: The Italian Sea Group, regulated press release, 2 November 2026, distributed on the authorised eMarket SDIR platform. The company also lists the release in its investor-relations archive. Figures and procedural steps are proposed, not finalised transactions.
Earlier Superyacht Guide coverage: TISG disclosed five binding asset bids in October. The present article records the later 2 November board decision, without treating the proposed sale as completed.
Lead illustration: Marina di Carrara harbour by Albarubescens / Wikimedia Commons, 2017, licensed under Creative Commons Attribution-ShareAlike 4.0. Image resized; the adapted image is distributed under the same licence. This is a locality photograph, not a photograph of TISG assets or a completed acquisition.
Continue reading
Marine Results International has become a RINA Approved Service Supplier for mast and rigging surveys with no restriction on yacht size or rig type, …
How owner deposits and stage payments help fund superyacht construction, why the model carries risk and what real shipyard cases teach buyers.
Royal Hakvoort Shipyard has confirmed that the 38.25-metre motor yacht Soprano has returned for maintenance and what the builder describes as her ten-year Lloyd's …
With the 16 November Marine Impact Lab approaching, organisers have detailed two practical workshops and eight topic tables covering materials, propulsion, finance and the …
Superyacht Guide
Continue into the wider Superyacht Guide.
Business opportunities · Superyacht Guide
Companies serving the superyacht market can discuss clearly identified advertising, sponsorship and business-profile opportunities. Commercial activity remains separate from independent editorial coverage.